Core banking software for cooperative banks, with mobile banking and digital KYC built in
One core banking platform and one general ledger for deposits, lending, members and branches, with mobile banking, UPI payments and RBI-aligned digital KYC running on the same core.
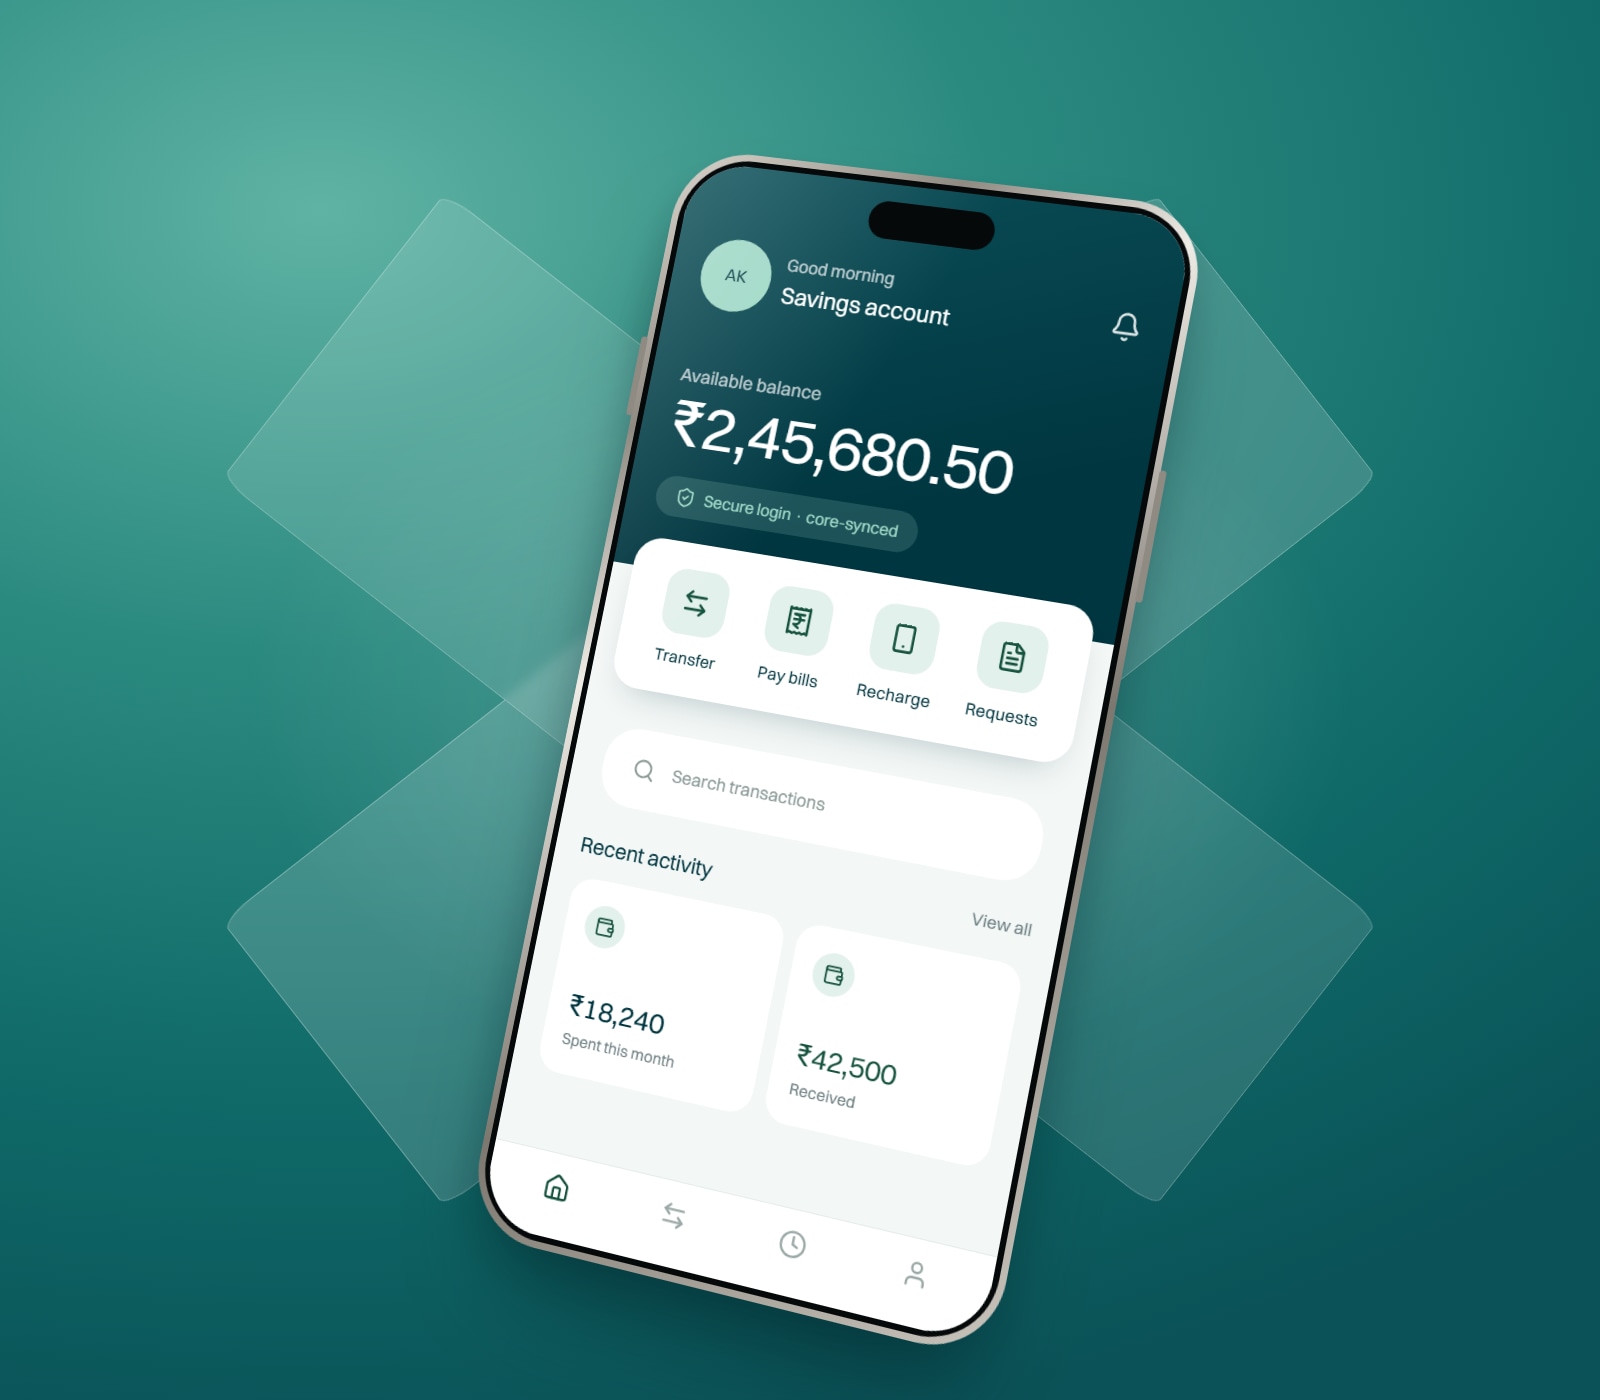
Tizora builds core banking software for cooperative banks and regional banks in India. Our cooperative bank software replaces disconnected systems with one core and one general ledger, and connects mobile banking and digital KYC to it through APIs.
Measured results from our digital KYC solution for banks
A 140-branch regional bank in India, measured over 90 days and 29,400 onboardings, from the platform audit log and branch MIS reports. Results will vary. See how the bank cut account opening to under 5 minutes
One core, every channel: a core banking solution built for cooperative banks
Many cooperative banks run deposits, loans, members, reconciliation and reporting on separate systems that do not share one ledger. We build one core banking platform for all of it, then connect the digital banking solutions your customers use, mobile banking and digital onboarding, to the same core, so every channel follows the same banking rules and the same audit trail.
- Built for
- Cooperative and regional banks in India
- Covers
- Core banking, mobile banking, digital KYC
- Integrates with
- Existing core, LOS and CRM through APIs
How we approach core banking modernization
What our cooperative bank software covers
Core banking and general ledger
Deposits, lending, member management, share capital and dividends, reconciliation, branch operations and reporting on one platform and one ledger.
Mobile banking app development
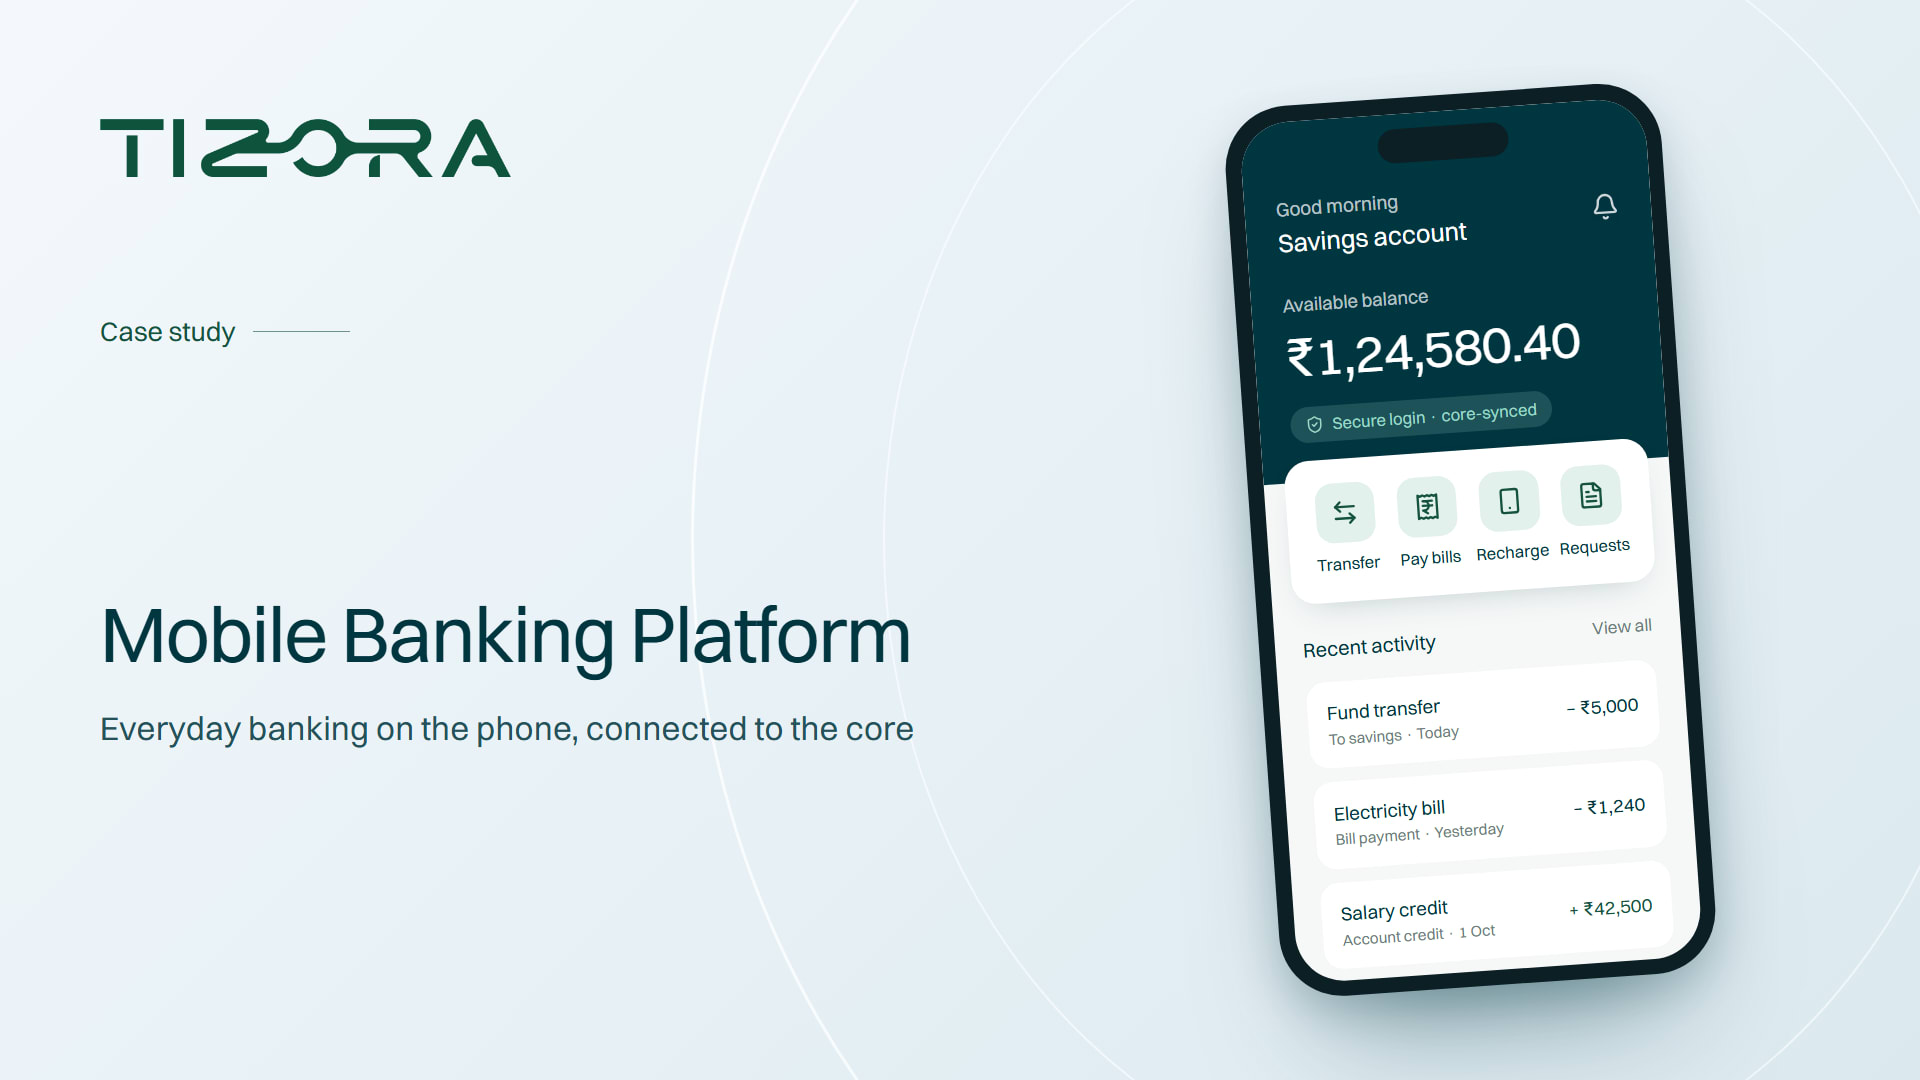
iOS and Android apps for balance checks, transfers, bill payments and service requests, with UPI, IMPS, NEFT and RTGS. Every action is validated by core banking rules.
Digital KYC solution for banks
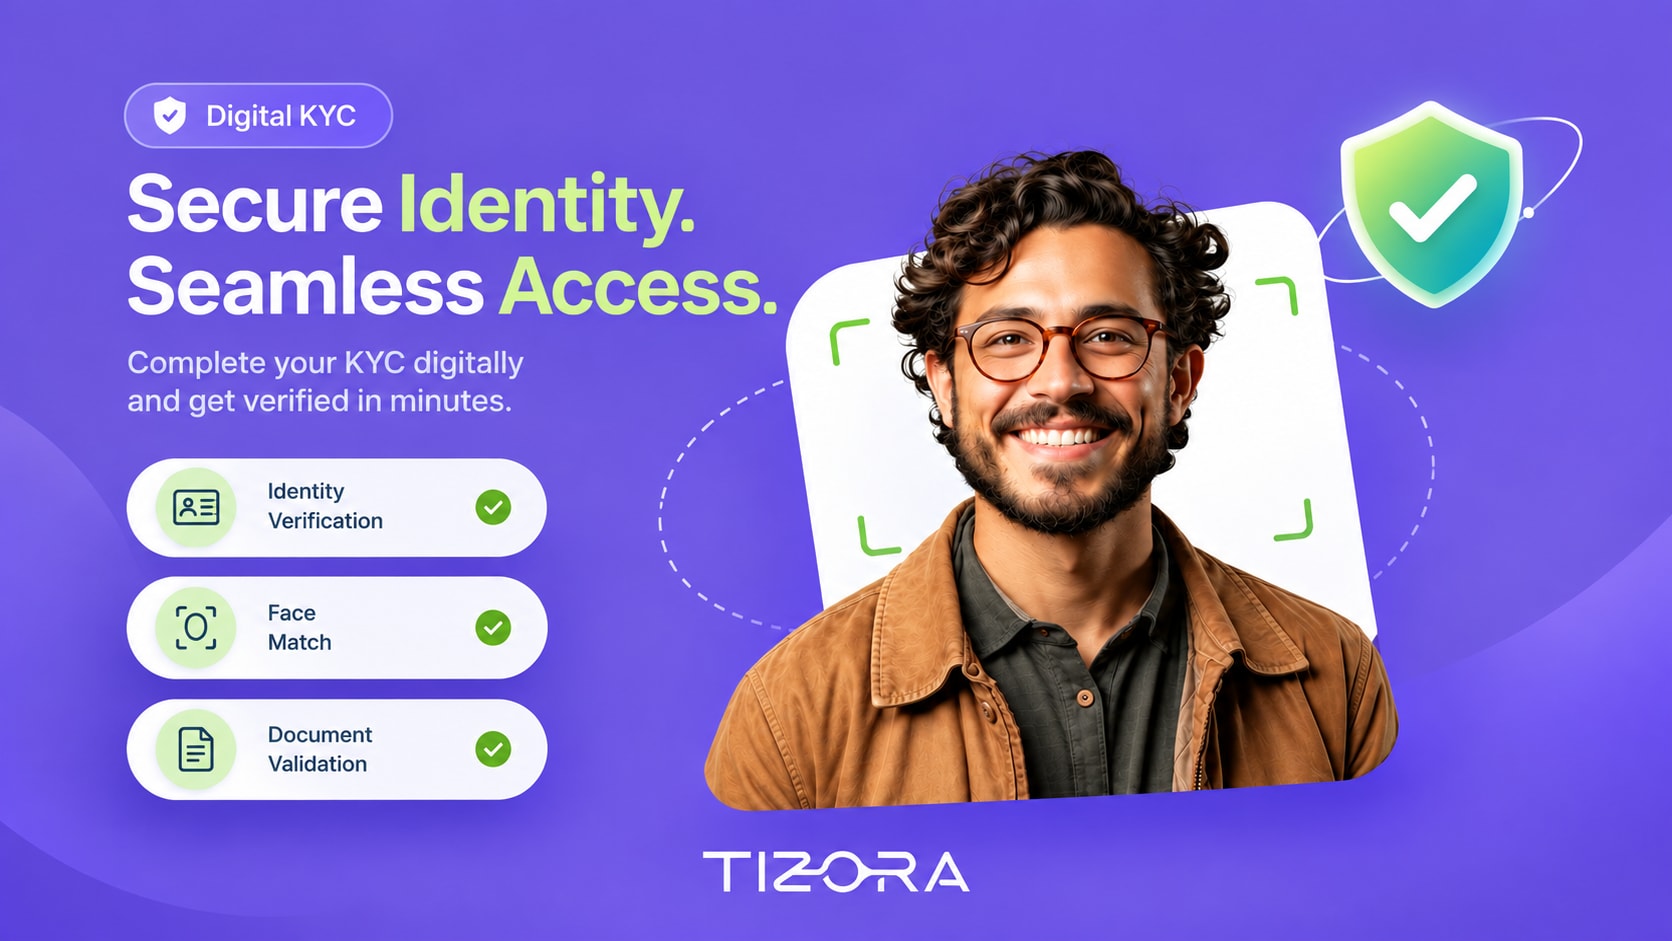
One onboarding flow with video KYC (V-CIP), Aadhaar eKYC, document OCR, officer-assisted digital KYC and eSign, on customer phones and branch tablets.
Do you need to replace your core banking system to go digital?
No. In our digital KYC project, a 140-branch bank kept its existing core banking system. A KYC API connected the new onboarding flow to the core, the loan origination system and the CRM. Banks that do want a new core can move one module at a time, with digital channels connected first.
How we deliver banking software for cooperative banks
Discovery
We review branch operations, products, existing systems and regulatory requirements.
Design
We design the product rules, ledger and integration APIs for your core, LOS and CRM.
Build and test
We build in stages and test each module against your banking rules before it reaches branches.
Branch rollout
We roll out branch by branch with staff training, and keep a full audit trail from day one.
Core banking software for cooperative banks in practice

Built for how cooperative banks work
- Member, share capital and dividend management alongside deposits and loans.
- Configurable product and interest rules without code changes.
- Open APIs (REST with OpenAPI) for your LOS, CRM and payment rails.

Engineering principles for banking software
Audit trail on every transaction: Every state change is written to an append-only audit log.
One set of banking rules: Mobile and branch actions are validated by the same core rules, and channels hold no separate copy of account data.
Secure by default: Multi-factor authentication, device binding and session controls on customer channels.

Who our cooperative bank software is built for
- Core banking
- deposits, lending, members, share capital and dividends on one platform and one ledger
- Mobile banking
- UPI, IMPS, NEFT and RTGS, validated by core banking rules
- Digital KYC
- video KYC (V-CIP), Aadhaar eKYC, document OCR and eSign
Cooperative and regional banks in India that run core operations on several disconnected systems, want mobile banking with UPI, or need RBI-aligned digital onboarding without replacing everything at once. We work alongside your in-house IT team or your existing banking IT solutions provider.
FAQ
Core banking and digital KYC FAQs
It runs a bank's day-to-day operations on one platform and one general ledger: deposits, lending, member management, share capital and dividends, reconciliation, branch operations and reporting. Tizora builds this for cooperative and regional banks, with mobile banking and digital KYC connected to the same core.
No. In our digital KYC project, a 140-branch bank kept its existing core banking system, and a KYC API connected the new onboarding flow to the core, loan origination system and CRM. Banks that want a new core can move one module at a time.
V-CIP is the video-based customer identification process that the Reserve Bank of India permitted in 2020 as a consent-based way to identify customers remotely. A bank official verifies the customer over a live video session, and the session is recorded and time-stamped.
Video KYC (V-CIP) verifies a customer remotely over a live video call with a bank official. Digital KYC usually means an authorised officer captures the customer's live photo and identity document through an app. Our onboarding flow supports both, along with Aadhaar eKYC, document OCR and eSign.
Through APIs. In our mobile banking platform, the app is an experience layer that holds no separate copy of account data, and every action is validated by the core banking rules before it is posted.
The mobile banking platform we built supports UPI, IMPS, NEFT and RTGS payments, along with balance checks, transfers, bill payments and service requests.
Customer channels use multi-factor authentication, device binding and session controls, and every state change is written to an append-only audit log. In the digital KYC project, every onboarding step writes to an immutable audit log.
For a 140-branch regional bank in India, average account opening time fell from 3 days to 4 minutes 40 seconds and onboarding drop-off fell from 38% to 14%, measured over 90 days and 29,400 onboardings. Results will vary between banks.
Talk to a banking software development company that builds for cooperative banks
Tell us which systems run your branches today. We will show how one core, mobile banking and digital KYC could fit, and what it would take to move in stages. Tizora is a banking software development company working with banks in India. If you are comparing banking software development companies, ask us for the measured results behind the case studies above.
